Free webinar Tue 20 Oct, 7pm NZDT: The 5 Election Policies That Will Hit Property Hardest, Ranked by Party.Free election webinar Tue 20 Oct, 7pm. Save your seat
For Australians & Kiwi expats

Invest in New Zealand property - from Australia.

How Australians and Kiwi expats are building cashflow property portfolios in New Zealand - while Australia taxes investors out. Around 20% of our clients live overseas, and the whole model is built for investing from a distance.

Book a free 15-min callDownload the PDF guide
The shift

Two countries, moving in opposite directions.

The smart-money question for a property investor isn't "which suburb?" - it's "which country?" New Zealand: no stamp duty, no land tax, cheaper money - and Australians can buy freely. Across the Tasman, Australia is heading the other way: negative gearing wound back, the CGT discount ending, surcharges climbing, rates rising.

 
Australia
New Zealand
Stamp dutyOne-off state tax paid upfront when you buy
Payable - varies by state, often tens of thousands
None
Land taxAnnual state tax on the land you hold
Payable + rising foreign-owner surcharges
None
Capital gains tax
More tax coming - the 50% discount ends 1 July 2027
None if held 2+ years*
Official interest rateRBA cash rate vs RBNZ OCR
4.35% - three hikes in 2026 already
2.50%
1-year fixed mortgage
Around 6%+
From 4.65%
Can you even buy?
Foreigners banned from established homes to ~2029
Australians can buy freely

*General information comparing the two countries' tax systems, not personalised financial advice. Sold sooner than 2 years, it's taxed - and if you remain an Australian tax resident, Australia still taxes your worldwide income and gains. Check with your accountant. Rates as at July 2026: RBA / RBNZ; advertised 1-year fixed rates, major banks.

The part most people miss

As an Australian citizen, you are exempt from New Zealand's foreign-buyer ban. You can buy residential investment property in NZ freely - no special visa, no approval process. Most other overseas buyers can't. That door was never closed to you.
Straight talk

But aren't the yields lower in New Zealand?

Fair question - and the honest answer is the whole point. Off the shelf, often yes: New Zealand's average rental yields are lower than Australia's regional cashflow hotspots. That's not the opportunity here. We don't buy retail yield - we generate it. Our deals target 8%+ gross yield on single homes and 10%+ on multi-unit projects through renovation and the BRRRR strategy, where the return comes from the deal itself, not a tax break.

Sydney & Melbourne
~3–3.5%
New Zealand, market average
~4%
Wolfe Accelerate - single home
8%+
Wolfe Boardroom - multi-unit
10%+

Typical gross rental yield. The market hands you ~3–4%. We manufacture 8–10%+ through renovation.

The method

Cashflow Hacking™: we add the value in.

Our whole approach rests on one move: buy an ordinary existing house, then renovate to add value - most often by adding a bedroom within the existing footprint. A standard 3-bedroom rental earns 3-bedroom rent. But plenty of homes are hiding a 4th bedroom in an oversized lounge or an underused garage. Add it, and the same house re-rents and re-values as a 4-bedroom - lifting both the rent and the property's worth, without extending the building.

Buy

Off-market where we can. Over half of our clients buy properties the public never sees, through relationships built over years.

Renovate

A targeted, costed value-add - usually that extra bedroom - that lifts the rent and forces equity, delivered by vetted local builders and trades.

Rent

Re-let at the new, higher market rent the renovation unlocked - income that pays you and strengthens your servicing.

Refinance

Revalue the property and release some of the equity the renovation created - funds you can put toward your next deposit.

Repeat

Roll that released equity and the stronger rental income into the next purchase. Each deal makes the next one easier.

Before you buy

Thinking about a new build? Do your research first.

Right now, plenty of developers and buyers' agencies are pushing New Zealand new builds to Australian investors. Here's what they won't tell you: around 1 in 5 New Zealand townhouse resales now sell at a loss - and a glut of unsold new stock is still competing for buyers. Apartments are worse: 41% resell at a loss. (RNZ, May 2026 - CoreLogic data.)

 
A new build
Our way - value-add
What you pay
Full retail + the developer's margin
Existing property, often off-market
Equity at purchase
None - you paid market
Instant, manufactured by the reno
Gross yield
~4%, usually cashflow-negative
8–10%+, cashflow-positive
The market
Oversupplied and discounting
The reno makes the return, in any market
Leans on
Tax perks and hoped-for capital growth
The renovation, not a tax break
The bottom line

A new build makes you the developer's exit. We make you the investor - buying existing property and manufacturing the return yourself. You own the margin, not the developer.

Hero case study · Boardroom Hands-Free

Kaveen: a tired 3-unit block turned into a 10%+ cashflow machine.

A multi-unit, done-for-you project we sourced, renovated and tenanted end to end for an Australian investor - while he stayed in Australia the whole time.

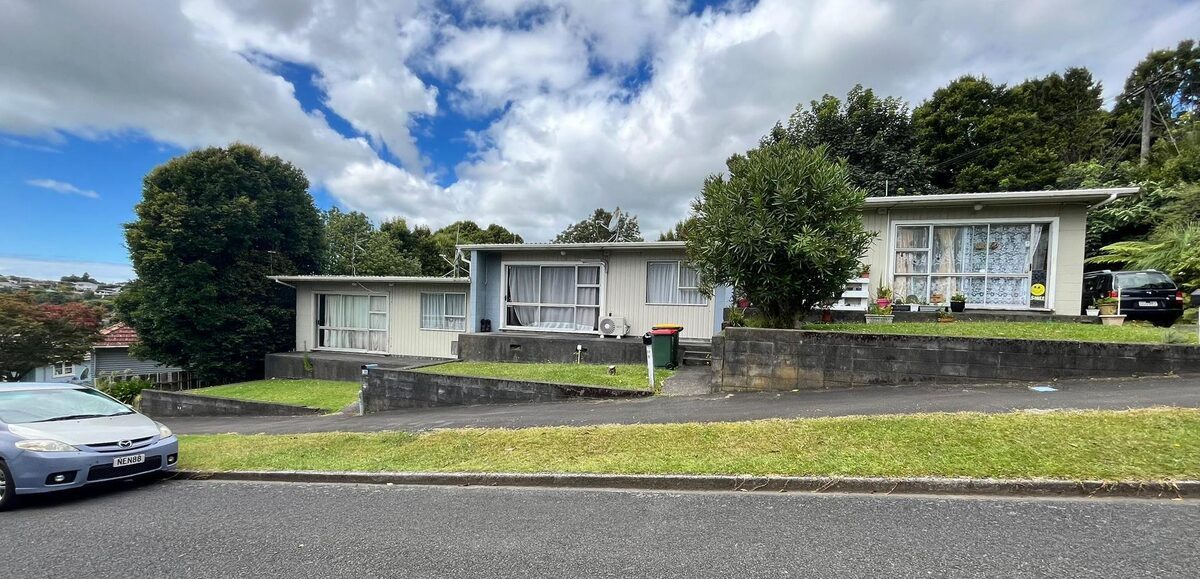
Three-unit block, fully renovated by the Wolfe Property Power Team
Three units, fully renovated by our Power Team - run entirely from Australia
$700,000
Purchase price - 3 units
$150,000
Renovation spend
$1,300,000
Revaluation
~$450,000
Equity created
$560
Rent per unit, per week
10%+
Gross yield
While residing in Australia, I needed someone I could trust to handle the entire process - from sourcing the right property to managing a full-scale renovation - and she exceeded my expectations in every way.
Kaveen · ★★★★★ Google review
Case study · Investing remotely

Christchurch: $175,000 of equity from one renovation.

This client invested remotely - leaning on our coaching and Power Teams rather than being on the ground - and turned a tired, low-yielding rental into a high-performing one. Bought at $420,000, a targeted value-add renovation, revalued at $650,000. The rent climbed 83% - $20,800 to $38,000 a year - and the gross yield landed above 8%.

$420,000
Purchase price
$650,000
Post-renovation valuation
$175,000
Net equity gain
+83%
Rent increase

See more real client projects →

Why distance doesn't matter

You don't have to live where you invest.

90% of our clients already invest in New Zealand regions they don't live in. Whether you're in Brisbane, Perth or Balclutha makes no practical difference - the whole model is built to run remotely. From Whangārei to Dunedin, every project runs through vetted local Power Teams - brokers, builders, trades, property managers and agents. They are your eyes, hands and feet on the ground, so you can buy where the best deals are, not just where you happen to live.

Off-market deal flow

Deal sourcers briefed with your criteria bring opportunities to you - no flights required for open homes.

Power Teams from Whangārei to Dunedin

Builders, inspectors, valuers and property managers do the boots-on-ground work, from due diligence to reno completion.

Decisions with full information

Rental appraisals, reno quotes and due diligence summarised clearly before anything goes unconditional.

We had a really great experience working with Ilse Wolfe while buying multiple units in New Zealand from Australia… Her Power Teams on the ground made a huge difference - everything was well coordinated, and we always felt in the loop without needing to chase things up… we were able to pull out almost all of the cash we initially put into the deal.
Ramesha · Boardroom client, Australia · Google review
Webinar replay

Watch the Australia webinar, free.

Ilse and Tasman Finance Partners on how Australians are buying cashflow-positive property in New Zealand: lending from across the ditch, the yields, the tax position and real client deals. Recorded exactly as it ran.

Register for the next live webinar →

Done for you

Hands-Free: we build your NZ portfolio - you just own it.

Our Hands-Free service was built for time-poor CEOs, All Blacks and other professional athletes who wanted everything property builds - without the time, or the learning curve. Today it's open to any qualifying client, and it's tailor-made for investing from Australia. Our team drives the entire deal on your behalf - sourcing (often off-market, before the public ever sees it), negotiating, planning and project-managing the full renovation. You stay in control of the outcome without ever being on the tools or on site.

Accelerate, Hands-Free
Your first NZ deal done for you.
  • A single home, value-add, targeting 8%+ gross yield
  • The on-ramp - we source, negotiate, renovate and tenant it
Boardroom, Hands-Free
Our flagship, for investors ready to move serious capital.
  • Multi-unit, portfolio-level projects targeting 10%+ gross yield
  • Fully managed end to end - you approve, we execute

How Hands-Free works, in detail →

Who you'd be working with

From $5,000 to a $20M portfolio - built from scars, backed by results.

Ilse Wolfe went from $5,000 to a multi-million-dollar portfolio before 40 - but the lesson that built this business came from a mistake. For her first five years she chased capital growth and ignored cashflow. It caught up with her: the family ended up in a cashflow hole deep enough that they moved in with the in-laws to dig out. As she puts it, you can't buy groceries with capital gains. That's when she built the Cashflow Hacking™ framework - and rebuilt, into 30+ rentals that pay her. Featured in the NZ Herald, BusinessDesk and on 1News.

20 yrs
Investing & coaching
500+
Renovations overseen
$150M+
In property deals
Focus on cashflow and the equity follows. The portfolio should fund your lifestyle - not the other way around.
Ilse Wolfe
Investing from Australia · FAQ

The questions Australians ask us first.

Can I get lending for a New Zealand property while I live in Australia?

Yes - in most cases this is done in two parts. An Australian lender releases equity from your Australian property (this becomes your deposit and renovation fund), and a New Zealand bank lends the balance against the New Zealand property, assessing your Australian income.

We're property coaches, not mortgage brokers, so we don't arrange lending ourselves. What we do is introduce you to a trans-Tasman mortgage broker who structures this every week, and get your numbers confirmed before you look at a single property.

Will New Zealand banks lend against my Australian income?

Generally, yes. New Zealand lenders assess Australian income for servicing, converted into NZ dollars (some apply a buffer to the exchange rate). Policies differ from lender to lender, which is exactly why we start every Australian client with a broker conversation rather than a property search.

How much equity do I need to invest in NZ from Australia?

As a working guide, our Australian clients typically bring the equivalent of around 30% of the purchase price plus a renovation fund, usually released from equity in their Australian property. For a single-home Accelerate project that's roughly AUD$150,000+ of usable equity; multi-unit Boardroom projects need considerably more.

Some New Zealand lenders will accept a lower contribution depending on your income position and the quality of the property. Your broker confirms the exact figure for your situation.

Can I use my superannuation to buy property in New Zealand?

In most cases, no - not directly. Buying residential property through super involves self-managed super fund rules and borrowing restrictions that are outside what we do, and we don't provide financial advice. If super is your main source of capital, speak with your accountant or a licensed financial adviser before assuming it's available. Most of our Australian clients fund their New Zealand purchase from home equity instead.

Will I pay tax in Australia on a New Zealand investment property?

If you're an Australian tax resident, Australia generally taxes your worldwide income - so New Zealand rental income and any gain on sale usually need to be declared in Australia, with credits for tax already paid in New Zealand where applicable. New Zealand itself has no general capital gains tax, but it does have bright-line and property-trading rules, and your visa or residency status can change the picture.

We are not tax advisers. We introduce every Australian client to an accountant who works across both systems, and we recommend getting that advice before you buy.

Should I buy in my own name, a company or a trust?

It depends on your circumstances on both sides of the Tasman - there's no universal answer. Lending is broadly similar across structures, so the decision is mainly a tax and asset-protection one, best made with a New Zealand-based accountant and lawyer who understand Australian residents. We help you get that advice lined up before you sign anything.

Do you buy for capital growth or yield?

Both - but cashflow comes first. Every property is chosen so it's cashflow-positive from day one after the renovation, verified in due diligence before you go unconditional. The renovation creates the equity uplift at the same time. In practice we push whichever side of your balance sheet is weaker: if you're short on cashflow, we solve that first; if you're short on equity, we prioritise the uplift.

Do you do quick flips - buy, renovate and sell within months?

No. Our model is buy, renovate, rent, refinance and hold. Holding is what compounds: the renovated property pays you every week, and the released equity funds the next deal. Selling quickly in New Zealand can also bring bright-line or property-trading tax treatment into play. Some properties can be split into separate titles later as a second-round value-add - but that's a hold strategy, not a flip.

Where in New Zealand do you buy for Australian clients?

Almost anywhere except Auckland and Queenstown - that's where the yield is. We have Power Teams in all regions from Whangārei to Dunedin, and 90% of our clients already invest somewhere they don't live. We don't publish a target-town list (it moves with the market and our deal flow), but we'll talk specifics on your call.

Can you manage the whole thing for me from Australia?

Yes. Around 20% of our clients live overseas and the model is built for distance: deal sourcers bring opportunities to you, local Power Teams handle inspections, renovation and tenanting, and you approve the decisions with full information. If you'd rather not be involved day to day, the Hands-Free option means we run the entire project and you simply own the result.

Do you take commissions from builders, brokers or other suppliers?

No. We are paid only by you, our client. We take no commissions, kickbacks or referral fees from builders, trades, brokers, agents or anyone else we introduce you to - so the advice you get is the advice we'd give ourselves.

How long does the process take from Australia?

Typically 3-6 months from offer to rent-ready. Lending pre-approval on both sides usually takes a few weeks, sourcing depends on your criteria and the market, and the renovation itself is generally 4-8 weeks once you've settled. You don't need to fly over at any point - most Australian clients never see the property until it's finished, if at all.

Should I ask my Australian broker to start an equity release now?

Knowing your usable equity is the sensible first step - it tells you what you can buy and what to say no to, before you get emotionally attached to a property. We don't give lending advice, but we can connect you with a broker who works across both countries so the Australian equity release and the New Zealand purchase lending are planned together, not in isolation.

Read the full FAQ - every question, answered

The best deals aren't in your backyard. Ours never were either.

Book a free, no-obligation 15-minute call. We'll look at your goals and position, and show you what a New Zealand cashflow portfolio could realistically look like for you.

Book a discovery call

Prefer to read later? Download the PDF guide

Wolfe Property Coaching provides property investment coaching and education. It is not financial, tax, or legal advice and does not constitute a recommendation to buy any specific property. Australian and New Zealand tax settings referenced reflect publicly reported policy as at July 2026 and may change - please seek independent professional advice for your circumstances.